Tag Archives: agri finance

post-harvest finance

Post-Harvest Finance: What Happens After the Crop Leaves the Farm?

October 08, 2026

The journey for a farmer never ends at harvesting the crops. Instead, once the crop is harvested, another question arises: How to manage money while the crop is still in storage?

Usually, a farmer wants to wait for a better market price instead of selling immediately. Similarly, a trader may need working capital to purchase the next lot of commodities. A processor may need funds to maintain inventory until production or sales take place. In each case, the commodity has value, but that value is tied up in physical stock.

This is where warehouse receipt finance, a part of post-harvest finance, can make a practical difference.

India’s agricultural credit ecosystem is already expanding to address such needs. The government’s Ground Level Credit target for agriculture and allied activities has been set at ₹32.5 lakh crore for 2025–26, with a dedicated ₹10,000 crore sub-target for loans against electronic Negotiable Warehouse Receipts (e-NWRs).

Why does post-harvest finance matter?

A farmer already spends money on seeds, fertilisers, labour and other inputs. Once the crop is harvested, there may be additional expenses for transportation, storage, processing or trading. Selling immediately can provide liquidity, but it may also mean accepting a price that is not ideal. This is particularly relevant because post-harvest losses continue to affect agricultural commodities. A 2022 NABCONS study covering 54 commodities estimated losses of 3.89–5.92% for cereals, 5.65–6.74% for pulses and 2.87–7.51% for oilseeds.

Better storage and access to finance can work together. When commodities are stored properly and the owner has access to working capital, there can be greater flexibility to decide when and how to sell.
agriculture finance

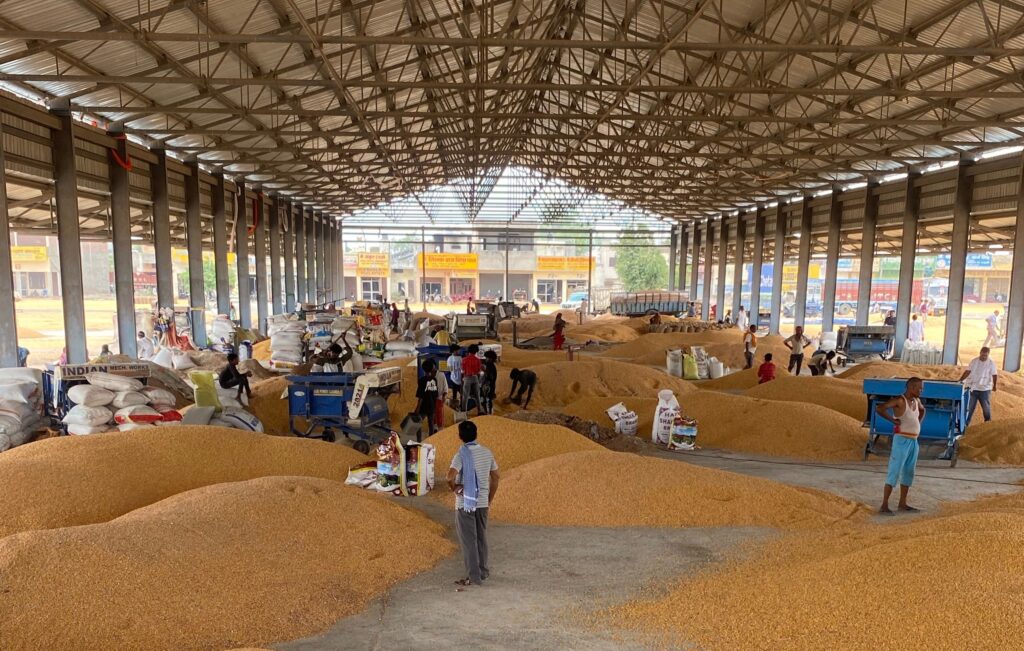
What happens when a crop enters a warehouse?

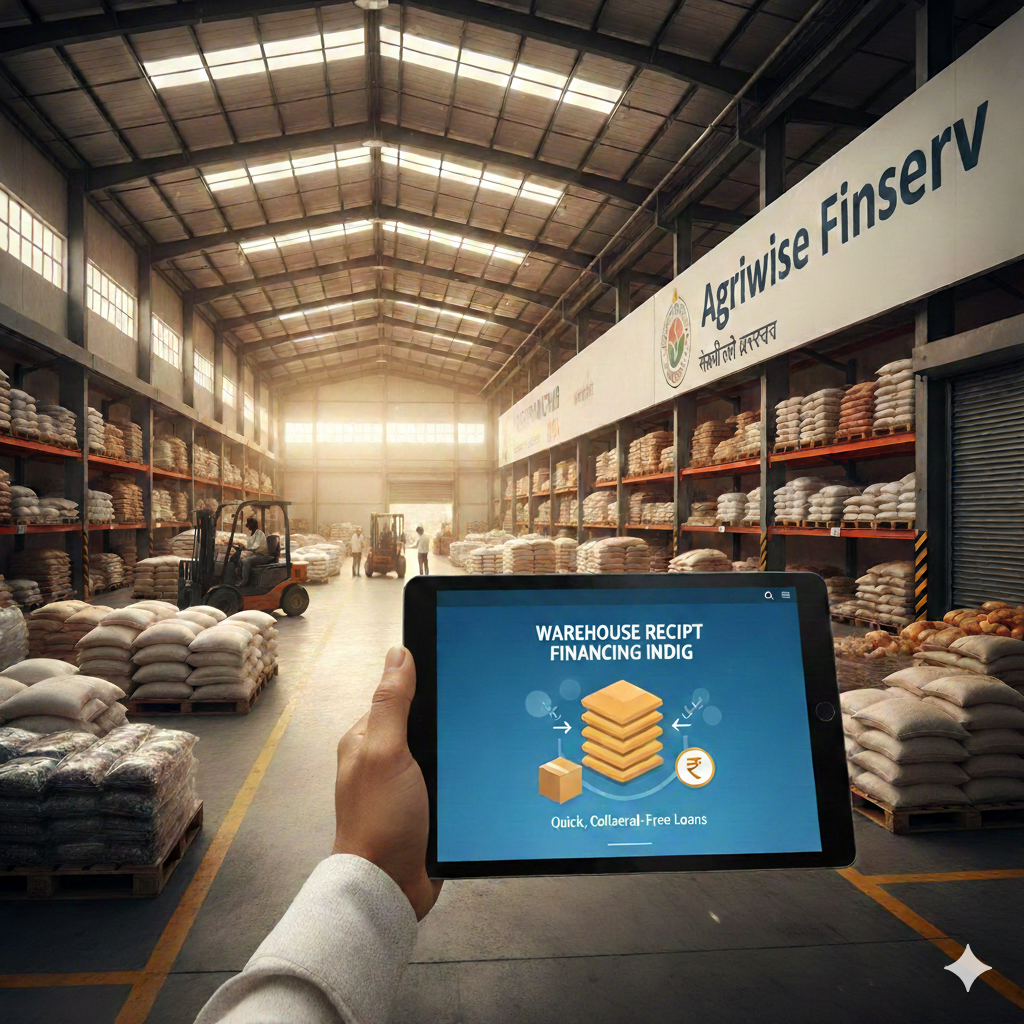
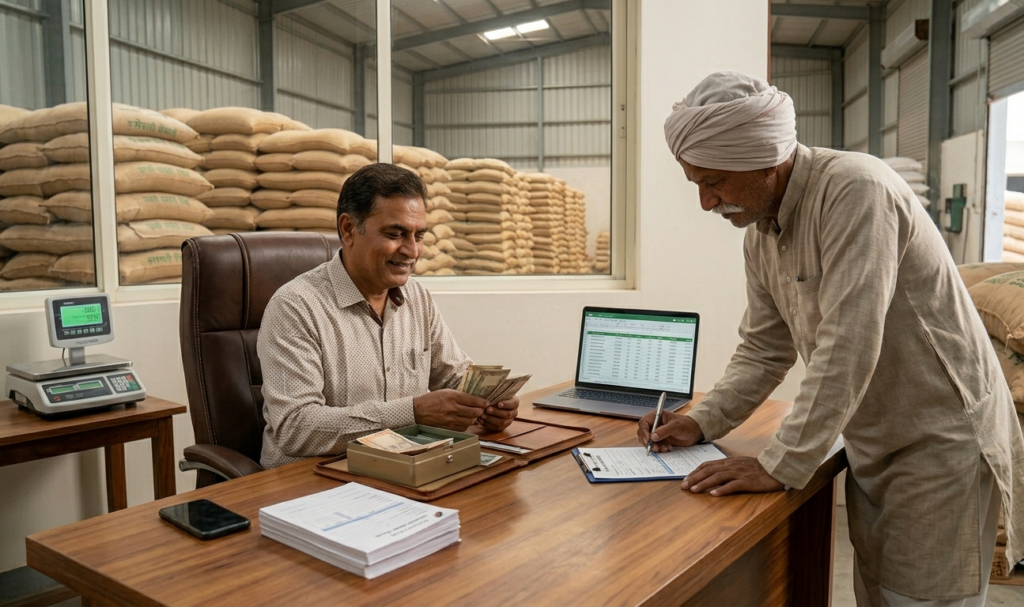
Once agricultural commodities are stored in a professional warehouse, the stock can be documented through a warehouse receipt. The receipt provides information related to the commodity held in storage and establishes a basis for financing against eligible inventory.

Instead of selling the commodity immediately to generate cash, an eligible borrower can use the stored inventory as the basis for short-term financing, subject to the lender’s assessment and applicable terms. This can be useful for farmers, traders and processors who have valuable inventory but need liquidity for their next business requirement.

The government has also been actively supporting this financing model. The Credit Guarantee Scheme for e-NWR Based Pledge Financing was introduced with a ₹1,000 crore corpus to encourage post-harvest lending against electronic warehouse receipts and reduce the risk for lenders.

How Agriwise’s Warehouse Receipt Finance works

Agriwise Finserv is an RBI-registered NBFC focused on financing the agriculture and MSME segments. It offers Warehouse Receipt Finance to eligible farmers, agricultural commodity traders and processors requiring short-term working capital against Staragri warehouse-stored commodities. 

The loan provides:

  • Loan amount up to ₹10 crore for short-term working capital needs
  • Loan-to-Value (LTV) of up to 75% of the value of goods pledged or covered by the warehouse receipt
  • Loans up to ₹5 crore without financial documents, subject to applicable eligibility and assessment
  • Access to an extensive pan-India network of StarAgri professional warehouses

Who can benefit from Warehouse Receipt Finance?

Farmers: Farmers who store eligible commodities can potentially access liquidity without having to sell their produce immediately. This can provide greater flexibility around post-harvest expenses and market timing.

Agricultural Commodity Traders: Traders often need working capital to purchase additional inventory while existing stocks are still being held. Finance against warehouse-stored commodities can help support this cycle.

Processors: Processors may need to maintain adequate raw-material inventory before it enters production. Working capital against stored commodities can help them manage procurement and operational cash flows.
agriwise finance

Why professional warehousing matters

Finance against stored commodities depends on the inventory, which makes the quality of the warehouse and the systems used to monitor commodities important. A professional warehouse can provide structured storage, inventory records, commodity monitoring and documentation. When storage and finance are connected, the physical commodity becomes a recognised asset that can support working capital.

This is also why the government’s policy focus increasingly connects warehousing with agricultural finance. The Credit Guarantee Scheme for e-NWR-based pledge financing specifically aims to encourage scientific storage, improve liquidity and expand post-harvest lending.

Post-Harvest Finance is crucial in India

Instead of a farmer or trader being forced into an immediate sale because cash is required, an eligible borrower can potentially access working capital while the commodity remains stored. This can help separate the need for liquidity from the decision to sell. For an agricultural economy as large and diverse as India’s, that distinction matters.

As agricultural credit expands and electronic warehouse receipts become a stronger part of the financing ecosystem, warehouse receipt finance can play an increasingly important role in connecting stored commodities with working capital. For farmers, traders and processors, the journey of a crop can become the foundation for the next stage of the business with the right storage and financial infrastructure.

FAQs

  • What is post-harvest finance?
    Post-harvest finance refers to funding available after agricultural produce has been harvested. It can help farmers, traders and processors meet working capital requirements related to stored commodities, processing, trading and other post-harvest activities.
  • What is warehouse receipt finance?
    Warehouse Receipt Finance is short-term financing provided against eligible agricultural commodities stored in a professional warehouse and covered by a warehouse receipt. It allows eligible borrowers to access working capital without necessarily selling their stored inventory immediately.
  • Who can apply for Agriwise Warehouse Receipt Finance?
    Agriwise’s WHR Finance is designed for agricultural commodity traders, processors and farmers who have eligible agricultural stocks stored in StarAgri professional warehouses, subject to applicable eligibility and assessment.
  • How much finance can be availed through Agriwise WHR Finance?
    Agriwise offers short-term working capital loans of up to ₹10 crore, with an LTV of up to 75% of the value of goods pledged or covered by the warehouse receipt.
  • Why is professional warehousing important for warehouse receipt finance?
    Professional warehousing provides structured storage and documentation of agricultural inventory. This helps establish greater visibility around the commodity that forms the basis of warehouse receipt financing and supports a more organised post-harvest financing process.
Agri Finance Technology: How Data is Making Agricultural Lending Smarter

September 24, 2026

What does a lender really need to know before financing an agricultural business? Traditional answers might include income, collateral, credit history and financial statements. But agriculture doesn’t always fit neatly into those boxes.

A trader’s financial position may depend on inventory. An FPO may have seasonal cash flows. A farmer’s repayment capacity can be connected to crop cycles. An agri-MSME may have healthy sales but face a temporary receivables gap.

This is why agri finance technology is becoming increasingly important.

India already has an enormous formal agricultural credit ecosystem. As of 10 August 2026, Kisan Credit Card applications stood at 763.6 lakh through commercial banks, 368.6 lakh through rural banks and 1,242 lakh through cooperative banks.

Can technology help make that credit more relevant, accessible and data-driven?

  • Agriculture generates more data than ever

Modern agricultural businesses leave digital footprints across multiple stages. There can be transaction records, warehouse information, commodity movement, land and crop data, invoices, payments and marketplace activity.

Individually, each data point may tell only part of the story. Together, they can provide a richer picture of the business.

  • Digital Public Infrastructure is changing credit access

India’s financial ecosystem is already highly digitised. The government reported 2,365.8 crore UPI transactions in July 2026, with a transaction value of ₹29.88 lakh crore across 741 banks.

Meanwhile, Jan Samarth had crossed 54.10 lakh applications worth ₹3,00,951 crore as of 1 June 2026, connecting borrowers with more than 300 lenders across 16 credit-linked government schemes. This digital infrastructure matters for agri finance because credit increasingly sits within a wider ecosystem of digital identity, payments, documentation and data.

Agri Finance Technology

  • Alternative data can add context

A traditional credit file may tell a lender about a borrower’s previous repayment behaviour. Alternative data can add operational context. For an agricultural business, that could include inventory information, warehouse receipts, trade flows or other business activity. 

  • Financing can be designed around the business cycle

A farmer may need funding before cultivation. A trader may need liquidity while commodities are in storage. A business selling to large buyers may need funds while waiting for invoices to be paid. That is why modern agri finance increasingly needs different products for different situations.

For example, Warehouse Receipt Finance can help businesses unlock working capital against stored agricultural stock, while Invoice Bill Discounting can convert eligible receivables into liquidity.

  • Technology can make the borrowing journey simpler

Digital applications, online eligibility tools and streamlined documentation can reduce friction during the financing journey. A technology-enabled approach is designed to make agri loans simpler and faster, and reports a faster approval TAT for its lending process.
That can matter particularly in agriculture, where a delayed funding decision may mean a missed procurement opportunity or a disrupted operating cycle.

finance technology

  • Agri Finance is expanding beyond farmers

One of the most important changes in agricultural finance is that the borrower isn’t always a farmer. The wider agricultural economy includes FPOs, input distributors, retailers, processors, traders, infrastructure businesses and other agri-linked MSMEs.

The numbers show how Agriwise lends to Agriculture lending 

Agriwise has disbursed more than ₹2,500 crore across 5,300+ customers, according to its 2026 company communications.

The company’s product portfolio also reflects the increasingly diverse financial needs of the agricultural economy, from warehouse-backed working capital and farmer finance to invoice financing, LAP and customised business loans.

As part of the wider StarAgri ecosystem, Agriwise can leverage information from areas such as AgriBhumi, collateral management and agricultural trade flows, helping bring greater context into financing decisions.

The Future of Modern Agri Finance

Technology won’t eliminate the complexities of agricultural lending. But it can change how those complexities are understood.

The future of agri finance technology lies in combining traditional financial information with relevant operational data, digital infrastructure and agricultural expertise.

For borrowers, that can mean financing solutions designed around real business needs rather than one-size-fits-all products. For lenders, it can mean a more complete view of the businesses they serve. And for agriculture as a whole, it can bring finance closer to the actual movement of crops, commodities, inventory and cash.

FAQs

  • What is agri finance technology?
    Agri finance technology refers to the use of digital platforms, data, analytics and technology-enabled processes to improve agricultural credit assessment, delivery and management.
  • How does data help agricultural lenders?
    Data from transactions, inventory, warehouses, crop information and other operational activities can provide additional context alongside conventional financial and credit information.
  • What is alternative data in agricultural lending?
    Alternative data refers to non-traditional information that can supplement conventional credit records, such as warehouse information, digital trade activity, satellite intelligence and supply-chain data.
  • What financial solutions does Agriwise offer?
    Agriwise offers Warehouse Receipt Finance, Invoice Bill Discounting, Farmer Finance, Loan Against Property, and customised Working Capital Loans.
  • Who can access Agriwise financing solutions?
    Agriwise serves stakeholders across the agricultural & MSMEs value chain, including farmers, FPOs, MSMEs, input distributors, retailers, manufacturers, agri-infrastructure businesses and other agriculture-linked enterprises.
farmer loan interest rates

What Factors Determine Farmer Loan Interest Rates in India?

September 17, 2026

Two farmers apply for agricultural finance. Their farms may be in the same district. They may even grow the same crop. Yet the interest rates or overall financing terms offered to them can differ.

Why?

Because farmer loan interest rates are rarely determined by a single factor. Lenders look at the type of loan, borrower profile, repayment capacity, collateral, tenure, credit history, and the risks associated with the financing requirement.

Understanding these factors can help farmers look beyond one question: “What is the interest rate?” and ask the more useful one: “What determines the rate I am being offered?”

First, there is no single farmer loan rate

Agricultural finance covers many different needs. A short-term crop loan, equipment loan, warehouse receipt finance facility and property-backed business loan do not carry identical risks or structures. Consequently, their pricing can differ.

Government-supported programmes can make certain categories of agricultural credit considerably cheaper.
For example, under the Modified Interest Subvention Scheme, eligible short-term Kisan Credit Card agricultural loans of up to ₹3 lakh have been available at 7% annually, with a 3% Prompt Repayment Incentive reducing the effective cost to 4% for farmers who repay on time. Beyond subsidised schemes, however, farmer loan interest rates depend on lender-specific pricing and borrower risk.

  • The Purpose of the Loan

What are you borrowing for?

Buying seeds for the coming season creates a very different financing requirement from purchasing machinery or expanding an agricultural business. Short-term working-capital requirements may be assessed around seasonal cash flows, while longer-term financing needs may involve a different repayment structure and risk assessment.

The clearer the purpose, the easier it becomes to identify an appropriate financing product.

low interest farm loans

  • Credit History and Repayment Behaviour

Past borrowing behaviour can influence future borrowing costs.

A strong repayment history indicates that the borrower has previously handled credit responsibly. Delayed payments, defaults or excessive outstanding debt may signal greater lending risk. This is why maintaining a healthy credit profile matters even in agriculture.

  • Repayment Capacity

A lender needs to answer a straightforward question: Can the borrower realistically repay this loan?

For agricultural borrowers, that assessment may consider income, cropping patterns, business cash flows, existing liabilities and the seasonal nature of earnings. Agriculture does not generate income like a monthly salary. Good agricultural lending therefore needs to understand when cash actually enters the borrower’s hands.

  • Whether the Loan is Secured/Collateral backed loan

Collateral can materially influence lending risk.

A secured facility may be backed by property, agricultural inventory or another acceptable asset. Because the lender has security against the financing, secured lending may be evaluated differently from unsecured credit.

Warehouse Receipt Finance is an interesting example. Instead of immediately selling produce after harvest, eligible borrowers can store commodities in an approved warehouse and use the warehouse receipt to seek financing against that inventory.

  • Loan Amount and Tenure (Short/medium/long term)

How much you borrow and for how long matters.

A ₹1 lakh seasonal requirement is fundamentally different from a multi-year, higher-value loan. Longer tenures expose lenders to risk for a greater period, while larger amounts require closer assessment of the borrower’s financial position and repayment capacity.

farmer loan interest

  • External Interest-Rate Benchmarks and Lender Policies

Borrower characteristics are only part of the picture.

Banks and NBFCs price loans within the broader financial environment. Benchmark lending rates, cost of funds, internal credit policies and risk premiums can therefore influence the final rate offered. That is why agricultural lending rates can change even when the farmer’s own circumstances remain broadly the same.

Agricultural credit is getting bigger and more diverse

Formal agricultural lending is becoming an increasingly important part of India’s rural economy. The policy framework requires applicable banks to direct at least 18% of Adjusted Net Bank Credit or equivalent exposure towards agriculture, including a 10% sub-target for small and marginal farmers.
As agricultural businesses become more connected with warehousing, processing, renewable energy and supply chains, the financing requirement is also becoming more specialised.

Agriwise’s role in this

Agriwise approaches agricultural finance around different borrower requirements rather than treating every need as the same loan.

Its portfolio includes Farmer Financing, Warehouse Receipt Finance, Loan Against Property, Supply Chain Finance and Customised Working Capital Loans. Agriwise has disbursed ₹2,500+ crore across 5,300+ customers and works with leading Indian banking partners.

For example, its Warehouse Receipt Finance offering provides short-term working capital against agricultural stocks stored in warehouses, with financing of up to ₹10 crore and LTV of up to 75%.

Look beyond the headline rate

The lowest advertised interest rate is not automatically the best financing decision. Farmers should also understand tenure, repayment frequency, processing charges, collateral requirements, prepayment conditions and the total cost of borrowing.

Ultimately, Farmer Loan Interest Rates reflect both the financial market and the borrower behind the application. Understanding what lenders evaluate gives farmers something more valuable than simply knowing a number. It helps them approach agricultural credit better prepared.

FAQs

  • What determines Farmer Loan Interest Rates in India?
    Rates can depend on the loan type, amount, tenure, collateral, credit profile, repayment capacity, lender policy and applicable government support.
  • Does credit history affect agricultural loan rates?
    Yes. Repayment history and existing debt can form part of a lender’s assessment of the borrower’s overall credit risk.
  • Are secured agricultural loans cheaper than unsecured loans?
    They may be priced differently because acceptable collateral can reduce lender risk, but actual rates depend on the lender and borrower profile.
  • What is Warehouse Receipt Finance?
    It allows eligible borrowers to obtain working capital against agricultural commodities stored in recognised warehouses instead of selling the produce immediately.
  • What agricultural finance products does Agriwise offer?
    Agriwise offers Farmer Financing, Warehouse Receipt Finance, Loan Against Property, Supply Chain Finance and Customised Working Capital Loans.

Agriculture Business Loans Under Priority Sector Lending: A Complete Guide

September 03, 2026

Agriculture needs capital long before it generates revenue.

A farmer may need money for inputs. A trader may need working capital to procure produce. A warehouse operator may need funds for infrastructure, while an agricultural business may need liquidity while waiting for invoices to be paid.

This is why agricultural credit is much broader than the traditional idea of a “farm loan”.

Agriculture Business Loans can support businesses operating throughout the agricultural value chain. And in India, Priority Sector Lending (PSL) plays an important role in directing institutional credit towards agriculture and other strategically important sectors.

Here is what agricultural businesses should understand.

What is Priority Sector Lending?

Priority Sector Lending is a framework established by the Reserve Bank of India (RBI) under which banks are required to direct a prescribed portion of their lending towards identified priority sectors.

These include agriculture, MSMEs, education, housing, renewable energy and certain other categories.

Under current RBI requirements, applicable commercial banks are required to allocate 18% of Adjusted Net Bank Credit (ANBC) or Credit Equivalent of Off-Balance Sheet Exposures (CEOBSE), whichever is higher, towards agriculture. A 10% sub-target applies to Small and Marginal Farmers. The purpose is to ensure productive sectors such as agriculture have stronger access to formal credit.

Which agricultural activities can qualify?

Agricultural lending under PSL is not restricted to crop cultivation. Depending on the borrower, activity, lender and prevailing RBI eligibility requirements, agriculture-related lending can cover farm credit, agricultural infrastructure and ancillary activities.

This broader framework is important because modern agriculture includes an entire commercial ecosystem: farmers, FPOs, processors, traders, warehouses, input businesses and other enterprises.

priority sector lending

Why do agriculture businesses need specialised loans?

An agricultural business rarely has the same cash-flow pattern as a conventional retail or service business. Procurement may be highly seasonal. Inventory may remain stored for months. Payments may depend on harvest cycles. Commodity prices can change between procurement and sale.

Consequently, Agriculture Business Loans should ideally reflect the actual working-capital cycle of the business rather than simply applying a generic lending structure.

Common financing requirements in agriculture

Different agricultural businesses require finance for different purposes.

  • Working Capital: Businesses purchasing commodities, inputs or raw materials may require short-term liquidity to manage procurement and operating expenses.
  • Warehouse Receipt Finance: Stored agricultural commodities may provide the basis for financing, allowing eligible borrowers to unlock liquidity against inventory rather than immediately selling produce.
  • Invoice Financing: Businesses supplying agricultural goods to buyers may face a gap between delivery and payment. Invoice-based financing can help manage this period.
  • Asset-backed Finance: Agricultural entrepreneurs may also require longer-tenure finance for business expansion, property-backed requirements or infrastructure investments.

Understanding the purpose of borrowing is therefore the first step towards selecting the right financing structure.

What do lenders evaluate?

Approval is never based only on whether a business operates in agriculture.

Lenders generally evaluate factors such as the borrower’s business profile, repayment capacity, cash flows, credit history, existing liabilities, documentation, collateral where applicable and the underlying purpose of the loan.

Agricultural lenders may additionally consider seasonality, commodity cycles, inventory quality and procurement or sales patterns. Good documentation and transparent financial records can therefore make a significant difference.

priority sector

How Agriwise supports agricultural businesses

As agricultural value chains become more organised, specialised lenders are developing financing solutions around their unique requirements.

Agriwise Finserv operates within this ecosystem with products including Warehouse Receipt Finance, Invoice Bill Discounting, Farmer Financing, Loan Against Property, and customised working-capital solutions.

Agriwise has disbursed more than ₹2,500 crore across 5,000+ customers and works with leading banking partners across India. Its customised working-capital approach is particularly relevant for agricultural enterprises because funding can be structured around the business profile, funding requirement, repayment capacity and working-capital cycle.

Choosing the right agriculture business loan

Before borrowing, businesses should ask a few practical questions: What exactly will the funds be used for? How quickly will the investment generate cash? Is the requirement seasonal or long-term? And what repayment structure fits the business cycle?

The right loan should not simply provide capital. It should fit the economics of the business.

As agriculture becomes increasingly connected with processing, warehousing, logistics and technology, access to appropriate formal credit will remain essential.

Agriculture Business Loans under India’s broader priority-sector ecosystem can help bridge that gap, enabling agricultural enterprises to invest, operate and grow with greater financial flexibility.

FAQs

  • What are Agriculture Business Loans?
    They are financing solutions designed to meet capital requirements of eligible businesses operating within agriculture and allied value chains.
  • Is agriculture covered under Priority Sector Lending?
    Yes. Agriculture is one of the major categories recognised under RBI’s PSL framework.
  • What is the PSL target for agriculture?
    Applicable banks have an agriculture target of 18% of ANBC or CEOBSE, whichever is higher, subject to RBI guidelines.
  • Can agricultural businesses get working-capital finance?
    Yes, subject to lender eligibility and assessment, working-capital facilities can support procurement, inventory and other operational requirements.
  • What financing solutions does Agriwise provide?
    Agriwise offers solutions including Warehouse Receipt Finance, Invoice Bill Discounting, Farmer Financing, Loan Against Property, and customised working-capital financing.

Priority Sector Agriculture Business Loans: Eligibility, Benefits, and How to Apply

August 06, 2026

If you run an agri-business in India, whether that’s a warehousing unit, a farm equipment dealership, an FPO, or a processing setup, there’s a good chance you qualify for credit that most borrowers never hear about at competitive terms: Priority Sector Lending (PSL) for agriculture. And in 2026, the rules around it just got a meaningful update.

What changed in 2026

The RBI’s revised Master Directions on Priority Sector Lending, effective from April 2025 and still shaping lending decisions through this year, mandate that banks earmark 18% of their Adjusted Net Bank Credit (ANBC) specifically for agriculture. That’s not a soft target. It’s a regulatory requirement, which means banks are actively looking for eligible agri-borrowers to meet it, not the other way around.

A few changes worth knowing if you’re applying in 2026:

  • Loans up to ₹100 crore per borrower are now eligible under agriculture infrastructure financing. That’s a big jump from earlier ceilings, opening PSL access to mid-sized agri-businesses, not just individual farmers.
  • On-lending through registered NBFCs and MFIs is capped at ₹10 lakh per borrower, which matters if you’re routing credit through an NBFC like Agriwise rather than a bank directly.
  • Banks can now co-lend with registered NBFCs (including Housing Finance Companies) for PSL purposes, which is expanding the number of channels through which agri-businesses can actually access this credit.
  • The overall PSL trading ecosystem, Priority Sector Lending Certificates (PSLCs), has scaled dramatically, with trading volumes rising from roughly ₹140 billion to over ₹8,951 billion in recent years, reflecting just how seriously banks are chasing agri-lending targets.

priority sector lending

Who’s actually eligible

Priority sector agriculture credit isn’t limited to individual farmers growing crops. The category spans a wide range:

  • Farm credit — individual farmers, Self Help Groups (SHGs), Joint Liability Groups (JLGs), and proprietorship firms directly engaged in agriculture and allied activities like dairy, poultry, and fisheries.
  • Agriculture infrastructure — cold storage, warehousing, market yards, and processing units, which qualify for the higher ₹100 crore ceiling.
  • Ancillary activities — inputs, equipment financing, and services that directly support agricultural production and post-harvest handling.

Why this matters for your business

PSL-backed loans typically come with better interest rates than standard commercial credit, precisely because banks have a regulatory incentive to disburse them. For agri-businesses that have historically struggled to access affordable working capital, warehousing operators, small processors, and equipment financiers, this is one of the few lending categories where the system is actively designed to say yes rather than no.

There’s also a compliance layer worth knowing: RBI now requires external auditor certification to ensure the same loan isn’t double-counted as PSL by both the originating bank and an intermediary NBFC. For borrowers, this mostly means cleaner, more transparent loan documentation.

How to apply

  • Identify your category: Confirm whether your business falls under farm credit, agri-infrastructure, or ancillary activities, which determines your eligible loan ceiling.
  • Prepare documentation: Business registration, land or asset ownership proof (where applicable), past financial statements, and a clear statement of end-use for the loan.
  • Choose your lending channel: Direct bank lending, NBFC on-lending, or co-lending arrangements all remain valid PSL routes, and the right one depends on your loan size & how quickly you need disbursal.
  • Submit and track: Most lenders now process PSL-eligible agri-loans through digitised workflows, which has meaningfully cut disbursal timelines compared to a few years ago.

priority sector

How Agriwise helps

Agriwise is built specifically to bridge this gap for agri-businesses that need working capital, warehouse receipt financing, or infrastructure credit but don’t always fit neatly into a traditional bank’s process. By combining sector expertise with faster, more flexible lending decisions, Agriwise helps eligible borrowers actually convert PSL eligibility into disbursed capital, turning a regulatory framework into real, usable business finance.

FAQs

  • What percentage of bank credit is mandated for priority sector agriculture lending in 2026?
    Banks are required to direct 18% of their Adjusted Net Bank Credit (ANBC) toward agriculture under RBI’s revised 2025 PSL directions, which remain in effect through 2026.
  • Can agri-infrastructure businesses like warehousing units access PSL loans?
    Yes. Agriculture infrastructure projects, including warehousing and cold storage, are eligible for PSL loans up to ₹100 crore per borrower under the current framework.
  • What is the loan cap for NBFC on-lending under PSL norms?
    On-lending through registered NBFCs and MFIs is capped at ₹10 lakh per borrower, though co-lending arrangements with banks can support larger financing needs.
  • Do PSL agriculture loans come with better interest rates than regular business loans?
    Generally yes, since banks have a regulatory incentive to meet PSL targets, which often translates into more competitive pricing for eligible agri-borrowers.
  • How can I apply for a priority sector agriculture loan through an NBFC?
    You’ll need to confirm your eligibility category, prepare business and financial documentation, and apply through an NBFC like Agriwise that specialises in structuring PSL-compliant agri-financing.
agri finance

10 Things Every Farmer Should Know About Agri Finance

July 23, 2026

Money worries and farming go hand in hand more often than they should. Whether it’s buying seeds before sowing season or holding onto produce until prices improve, timely access to credit can be the difference between a good season and a stressful one. Yet agri finance remains one of the most misunderstood parts of a farmer’s journey. Here are 10 things worth knowing before you take your next loan.

  • Agri finance is bigger than just crop loans
    Most farmers think of agri finance as the seasonal crop loan from a bank. In reality, it covers a much wider range. Warehouse receipt financing, loans against property, equipment and solar financing, and even working capital support for agri-businesses and FPOs. Knowing the full menu helps you pick what actually fits your need.
  • India’s agri credit flow has grown massively
    This isn’t a small, stagnant sector. Ground-level credit disbursed to Indian agriculture is set to touch Rs 32.50 lakh crore in FY 2025-26, more than four times the Rs 8 lakh crore disbursed in FY 2014-15, according to IANS. That’s over a decade of consistent, roughly 13% annual growth in the rural credit ecosystem.
  • Rural banking infrastructure is expanding too
    Access is improving alongside the credit itself. Rural bank branches grew over 35% to reach 56,193 by July 2025, and regional rural banks now operate more than 22,000 branches across 700 districts, meaning formal credit is reaching further into the Indian geographies.
  • Formal credit is cheaper than informal lending
    This one matters more than farmers often realise. Informal moneylenders typically charge anywhere from 24% to 60% interest, compared to the 12-18% range charged by agri-focused NBFCs. Over a full season, that gap can mean the difference between profit and debt.

  • Warehouse Receipt Finance can save you from distress sales
    If you’ve ever sold your harvest early just because you needed cash, warehouse receipt finance is worth understanding. It lets you store your produce in an approved warehouse and borrow against it, so you’re not forced to sell the moment prices dip right after harvest.
  • Loan Against Property isn’t just for big expansion
    While Agri LAP is often used for larger infrastructure or diversification projects, it’s also a practical option for funding equipment upgrades, land development, or allied ventures like dairy or poultry.
  • Solar and Equipment financing are growing fast
    With input and power costs rising, more farmers are turning to solar finance to cut long-term operational expenses. It is a sign that agri finance today goes beyond survival lending into genuinely productive investment.
  • Your land & farming data can work in your favour
    Digital credit assessment is changing how lenders evaluate farmers. Satellite-verified land intelligence and data-backed credit scoring mean even smallholder farmers with limited paperwork can now build a credible profile for faster loan approvals, rather than relying purely on collateral or lengthy documentation.
  • Rural consumption confidence is rising
    According to NABARD’s Rural Economic Conditions and Sentiments Survey (May 2026), about 77.2% of rural households reported higher consumption levels, reflecting a rise in purchasing power that shows deepening reach of formal rural finance.
  • Choosing the right partner matters as much as the loan itself
    A finance partner who understands farming cycles, commodity price swings, and post-harvest realities will structure your loan very differently than a generic lender. That contextual understanding often determines whether the loan actually helps you or adds pressure at the wrong time.

loans india

How Agriwise fits into this picture

Agriwise Finserv, the RBI-registered NBFC arm of the StarAgri Group, is built specifically around these realities. It offers a full suite of agri-focused lending products: Warehouse Receipt Finance, Agri Loan Against Property, Solar Finance, and Invoice Discounting/Supply Chain Finance for agri-MSMEs, designed to match how farming income actually flows through the year.

Agriwise has partnered with leading banks and financial institutions to widen access to capital, and draws on data from StarAgri’s broader ecosystem, including satellite-backed land intelligence through AgriBhumi, to assess creditworthiness fairly, even for smallholder farmers without extensive paperwork.

And because Agriwise operates within StarAgri’s warehousing and collateral management network, it also brings practical, on-ground understanding of storage, commodity value, and market timing, not just numbers on a loan application.

The Bottom Line

Agri finance is about borrowing the right kind of money, at the right time, from someone who understands your farming cycle as well as your balance sheet. With India’s formal credit ecosystem expanding rapidly, there’s never been a better time for farmers to move away from informal lenders and explore structured, transparent options like those offered by Agriwise, built for agriculture’s real needs. 

FAQs

  • What is warehouse receipt finance and how does it help farmers?
    It lets farmers store their produce in an approved warehouse and borrow money against it, so they aren’t forced to sell right after harvest when prices are typically lowest.
  • How is agri finance different from a regular personal loan?
    Agri finance is structured around farming cycles, harvest timelines, and commodity price patterns, rather than fixed monthly repayment schedules that don’t account for seasonal income.
  • Can smallholder farmers with limited documentation get agri loans?
    Increasingly, yes. Digital credit assessment tools, including satellite-verified land data, are helping lenders evaluate smallholder farmers fairly, even without extensive paperwork.
  • Why is formal agri finance better than borrowing from informal lenders?
    Informal lenders often charge 24-60% interest, compared to 10-18% from agri-focused NBFCs. That is a difference that can significantly affect a farmer’s profitability over a season.
  • What kind of agri finance products does Agriwise offer?
    Agriwise offers Warehouse Receipt Finance, Agri Loan Against Property, and Invoice Discounting/Supply Chain Finance for agri-MSMEs, among other structured lending solutions.
warehouse receipt finance

Why Warehouse Receipt Finance Could Become India’s Most Important Post-Harvest Financial Tool

May 28, 2026

Harvest season should ideally be the most rewarding time for farmers and agri-traders. But in reality, it often becomes the most financially stressful.

Why?

Because the moment crops arrive in the market, prices tend to come under pressure. Supply increases rapidly, storage access remains uneven, and many farmers are forced to sell immediately, not because they want to, but because liquidity cannot wait.

This is where one financial tool is becoming far more important in Indian agriculture than most people realise: Warehouse Receipt Finance.

At first glance, it may sound like just another lending product. But in reality, it has the potential to reshape how agricultural commodities are stored, financed, and traded after harvest.

And as India’s agricultural ecosystem becomes more integrated and data-driven, Warehouse Receipt Finance could emerge as one of the most critical pillars of post-harvest agriculture.

The real problem begins after harvest

India’s agricultural production continues to rise steadily. India has set a food production target of 362.5 Million Tonnes in 2025-26. But post-harvest liquidity continues to remain a major challenge across the ecosystem. Farmers, traders, processors, and agri businesses often require immediate working capital after harvest:

  • to manage operations,
  • repay short-term obligations,
  • fund procurement,
  • or plan the next crop cycle.

Without adequate financing access, many are forced into distress selling, offloading commodities immediately, even when market conditions are unfavourable. This affects not just farmers, but overall supply-chain efficiency.

So, what exactly is Warehouse Receipt Finance?

The concept is relatively simple.

When agricultural commodities are stored in a recognised warehouse, the depositor receives a warehouse receipt, a document representing ownership of the stored commodity. That receipt can then be used to access financing without immediately selling the stock.

In other words, commodities themselves become working capital. This changes the entire post-harvest dynamic. Instead of selling under pressure, farmers and agri businesses gain the flexibility to:

  • hold inventory strategically,
  • wait for better market conditions,
  • improve cash flow,
  • and manage supply-chain operations more efficiently.

And as India’s warehousing ecosystem becomes increasingly digitised through electronic Negotiable Warehouse Receipts (e-NWRs), the process is becoming more transparent and scalable.

warehouse receipt finance

Why is it important

Agriculture today is increasingly about timing, visibility, and liquidity. Modern agricultural supply chains move fast. Commodity prices fluctuate rapidly. Procurement windows are becoming more dynamic. Export opportunities can emerge suddenly.

In such an environment, immediate distress selling creates inefficiencies across the ecosystem. Warehouse Receipt Finance helps reduce that pressure. More importantly, it creates stronger integration between:

  • storage,
  • financing,
  • trade,
  • and supply-chain movement.

This is why the future of agricultural finance may increasingly depend on post-harvest intelligence rather than just conventional lending.
Globally, commodity-backed financing and inventory-linked lending models are gaining importance as supply chains become more data-driven and integrated.

Warehousing is becoming financial infrastructure

Traditionally, warehouses were viewed mainly as storage facilities. Today, they are becoming much more than that. Modern warehousing ecosystems now influence:

  • financing access,
  • commodity traceability,
  • collateral management,
  • procurement planning,
  • and supply-chain visibility.

This is especially important in agriculture because inventory itself carries significant financial value. When warehouses become digitised and inventory visibility improves, financing becomes faster, more transparent, and more scalable.

In many ways, warehouses are gradually evolving into financial infrastructure for agriculture. And that is one of the biggest structural shifts happening in the sector today.

How Agriwise fits into this ecosystem

As agricultural finance evolves, Agriwise Finserv is strengthening the connection between warehousing, trade, and liquidity. Agriwise offers Warehouse Receipt Finance solutions designed to help farmers, traders, and agri businesses unlock working capital against stored commodities instead of immediately liquidating inventory.

What makes this increasingly relevant is the broader integrated ecosystem surrounding it. As part of the larger StarAgri ecosystem, Agriwise operates within a connected agricultural infrastructure that includes:

  • warehousing,
  • collateral management,
  • digital agri trade,
  • and AI-led agricultural intelligence.

This integration becomes important because financing decisions in agriculture are becoming increasingly data-driven. Better warehouse visibility, digitised inventory systems, and stronger commodity intelligence can help create faster and more efficient post-harvest financing ecosystems.

Today, Agriwise has partnered with 25+ banks and financial institutions and has facilitated disbursements exceeding ₹2,500 crore across agricultural financing solutions.

The future of agricultural liquidity may be inventory-led

For years, agriculture focused heavily on production financing. But the next phase of agricultural finance may revolve around inventory financing. Because after harvest, commodities are not just produce sitting in storage. They are valuable, waiting to move through the supply chain.

And the ability to unlock liquidity without forcing immediate sale could become one of the biggest advantages in modern agriculture.

Warehouse Receipt Finance could become one of the most important financial tools supporting a smarter, more resilient, and more connected agricultural ecosystem in India.

FAQs

  • What is Warehouse Receipt Finance?
    Warehouse Receipt Finance allows farmers and agri businesses to access loans against commodities stored in recognised warehouses.
  • How does Warehouse Receipt Finance help farmers?
    It helps farmers avoid distress selling by enabling them to access liquidity without immediately selling stored produce.
  • What is an e-NWR?
    An electronic Negotiable Warehouse Receipt (e-NWR) is a digitised warehouse receipt issued against stored commodities in WDRA-registered warehouses.
  • Why is post-harvest financing important in agriculture?
    Post-harvest financing improves liquidity, supports better price realisation, and helps strengthen agricultural supply chains.
  • How does Agriwise support warehouse-backed financing?
    Agriwise offers Warehouse Receipt Finance solutions integrated with broader warehousing and agricultural ecosystems.

Disclaimer

The content published on this blog is provided solely for informational and educational purposes and is not intended as professional or legal advice. While we strive to ensure the accuracy and reliability of the information presented, Agriwise make no representations or warranties of any kind, express or implied, about the completeness, accuracy, suitability, or availability with respect to the blog content or the information, products, services, or related graphics contained in the blog for any purpose. Any reliance you place on such information is therefore strictly at your own risk. Readers are encouraged to consult qualified agricultural experts, agronomists, or relevant professionals before making any decisions based on the information provided herein. Agriwise, its authors, contributors, and affiliates shall not be held liable for any loss or damage, including without limitation, indirect or consequential loss or damage, or any loss or damage whatsoever arising from reliance on information contained in this blog. Through this blog, you may be able to link to other websites that are not under the control of Agriwise. We have no control over the nature, content, and availability of those sites and inclusion of any links does not necessarily imply a recommendation or endorsement of the views expressed within them. We reserve the right to modify, update, or remove blog content at any time without prior notice.

Agriwise: Making Financial Solutions Work Smarter for Indian Agriculture

April 16, 2026

Access to timely financial solutions can often make the difference between opportunity and missed potential in agriculture. Whether it’s a farmer planning the next crop cycle or a trader waiting to capitalise on market movements, liquidity plays a critical role.

Yet despite agriculture being one of the largest contributors to the economy, access to formal, timely credit remains fragmented for many stakeholders. This often leads to delayed decisions, missed market opportunities, and continued dependence on informal financing channels, a challenge widely highlighted by institutions like the Reserve Bank of India and NABARD.

That’s where Agriwise Finserv steps in.

As the financial solutions arm of StarAgri, Agriwise is built to simplify access to credit across the agri value chain, bringing together domain expertise, structured products, and technology-driven processes.

financial solutions

Finance That Understands Agriculture

Agriculture doesn’t follow a fixed calendar, and neither should financing.

Agriwise designs its offerings around real-world agri cycles, ensuring that credit is not just available, but also relevant and timely. Here’s how it supports different needs:

  • Warehouse Receipt Finance: Unlock liquidity without selling your produce, store now, and sell when prices are right
  • Loans Against Property (LAP): Access higher-value funding to expand operations or manage working capital
  • Invoice Bill Discounting: Convert receivables into immediate cash flow and keep business moving
  • Farmer Finance: Timely support for inputs, cultivation, and post-harvest requirements
  • Solar Finance: Invest in sustainable solutions while reducing long-term operational costs

These solutions are designed to align with agricultural cash flow cycles, enabling borrowers to manage both short-term needs and long-term growth plans more effectively.

Not Just Loans but Smarter Financial Solutions

What truly makes Agriwise stand out is how it blends finance with technology.

Because it is deeply integrated within the StarAgri and agribazaar ecosystem, Agriwise leverages insights from AgriBhumi, collateral management, and trade flows. This enables:

  • Faster and more informed credit assessments
  • Reduced reliance on traditional documentation
  • Better risk evaluation through supply chain visibility

This approach reflects a broader shift in agri-finance, where data-backed lending is increasingly becoming the norm.

And it doesn’t stop there.

financial solutions company

Agriwise also offers user-friendly tools like an EMI calculator, allowing borrowers to:

  • Estimate repayments in advance
  • Compare different loan scenarios
  • Plan cash flows with greater clarity

It’s a simple yet powerful feature, one that enhances transparency, improves decision-making, and builds trust even before a loan is availed.

Looking Ahead: The Future of Agri Finance

As agriculture becomes more data-driven and interconnected, the role of finance is evolving rapidly.

Digital adoption, supply chain integration, and policy-level push for financial inclusion are reshaping how credit flows into the sector, an evolution also emphasised in various reports  & publications.

Agriwise is positioned right at this intersection, combining:

  • Financial expertise
  • Supply chain intelligence
  • Technology-led innovation

The result is a more resilient, efficient, and accessible financial ecosystem for agriculture, where credit is not just available but truly aligned with the needs of those it serves.

FAQs

  • What is Agriwise and how does it support the agri sector?
    Agriwise Finserv is the financial solutions arm of the StarAgri ecosystem, offering structured credit solutions tailored to farmers, traders, and agri-businesses across the agricultural value chain.
  • What types of financing solutions does Agriwise offer?
    Agriwise provides a range of products, including warehouse receipt finance, loans against property (LAP), invoice bill discounting, farmer finance, and solar finance, designed to meet both working capital and long-term funding needs.
  • How does Agriwise utilise AgriBhumi for credit assessment?
    Agriwise leverages insights from AgriBhumi to assess farmers’ eligibility and credibility. These data-driven insights help banks and financial institutions make more informed lending decisions, thereby improving access to structured, reliable credit.
  • How does Agriwise use technology to improve access to finance?
    Agriwise leverages data from warehousing and supply chain systems within the StarAgri ecosystem to enable faster credit assessments, reduce paperwork, and improve transparency in lending decisions.
  • How does Agriwise help borrowers make informed financial decisions?
    Agriwise offers tools like an EMI calculator that allow users to estimate repayments, compare loan options, and plan cash flows, helping them borrow with greater confidence and clarity.

Disclaimer

The content published on this blog is provided solely for informational and educational purposes and is not intended as professional or legal advice. While we strive to ensure the accuracy and reliability of the information presented, Agriwise make no representations or warranties of any kind, express or implied, about the completeness, accuracy, suitability, or availability with respect to the blog content or the information, products, services, or related graphics contained in the blog for any purpose. Any reliance you place on such information is therefore strictly at your own risk. Readers are encouraged to consult qualified agricultural experts, agronomists, or relevant professionals before making any decisions based on the information provided herein. Agriwise, its authors, contributors, and affiliates shall not be held liable for any loss or damage, including without limitation, indirect or consequential loss or damage, or any loss or damage whatsoever arising from reliance on information contained in this blog. Through this blog, you may be able to link to other websites that are not under the control of Agriwise. We have no control over the nature, content, and availability of those sites and inclusion of any links does not necessarily imply a recommendation or endorsement of the views expressed within them. We reserve the right to modify, update, or remove blog content at any time without prior notice.

Working Capital in Agri Trade to Keep the Market Moving

March 26, 2026

A trader spots a good opportunity in the market. Prices are favourable, supply is available, and demand looks steady. On paper, everything makes sense.

But there’s a small problem. The capital isn’t available right away.

And in agriculture, that’s often enough to miss the opportunity entirely.

Because, unlike many other sectors, agri trade moves quickly. Prices shift, arrivals fluctuate, and decisions often need to be made in real time. In this environment, one factor influences everything: working capital.

Why Traditional Financing Doesn’t Always Fit

Traditional lending has played an important role in agriculture, but it doesn’t always align with how agri trade actually works.

Some common challenges include:

  • Approval timelines that don’t match market speed
  • Collateral requirements that not all participants can meet
  • Standard loan structures that don’t reflect commodity cycles
  • Limited flexibility in repayment and usage

For a trader or agri-business operating in a fast-moving market, these gaps can make financing less practical, even when it is available.

A Shift Toward Trade-Linked Financing

Instead of viewing financing as a standalone product, there’s a growing shift toward linking finance directly to trade activity.

In simple terms, credit is structured around what’s actually happening on the ground: procurement, storage, movement, and sale of commodities.

This approach includes solutions like:

  • Inventory-backed financing
  • Invoice bill discounting
  • Warehouse receipt-based lending
  • Supply chain financing models

The advantage here is that finance becomes more contextual and responsive, rather than rigid. It moves with the trade cycle instead of working around it.

Why Working Capital Matters Across the Value Chain

Working capital is often seen as a trader’s concern, but in reality, it affects the entire agricultural ecosystem.

When liquidity is constrained:

  • Farmers may face delayed payments
  • Traders may limit procurement volumes
  • Processors may slow down operations
  • Market activity overall becomes less efficient

On the other hand, when working capital flows smoothly:

  • Procurement becomes more active
  • Supply chains move faster
  • Price discovery improves
  • Market participation increases

In that sense, beyond being just financial support, working capital keeps the system moving.

How Agriwise Supports Working Capital Needs

As the need for more flexible, trade-aligned financing grows, platforms like Agriwise are helping bridge some of these gaps.

Agriwise focuses on offering financial solutions that are designed around the realities of agricultural trade, rather than generic lending structures. Its key offerings include:

  • Warehouse Receipt Finance: This allows businesses to access funding against stored commodities, helping them unlock liquidity without selling immediately.
  • Invoice Bill Discounting: By converting receivables into immediate cash flow, this solution helps businesses manage working capital more efficiently.
  • Loans Against Property (LAP): These provide access to larger, structured funding for expansion, procurement, or operational needs.
  • Farmer Finance: Designed to support agricultural cycles, helping farmers manage input costs and working capital requirements.
  • Solar Finance: Enabling investment in renewable energy solutions, particularly relevant for rural and agri-linked enterprises.

What ties these solutions together is their focus on flexibility and relevance, ensuring that financing aligns more closely with how agri businesses actually operate.

Looking Ahead

Agricultural markets are becoming more connected, more data-driven, and more time-sensitive.

In this environment, access to working capital is essential.

We’re gradually moving toward a system where:

  • Finance is linked to real trade activity
  • Credit decisions are faster and more informed
  • Solutions are tailored to specific stages of the value chain

And as this shift continues, Agriwise will play an important role in making financing more accessible, structured, and aligned with the needs of the agri ecosystem.

Because in the end, every transaction in agriculture, whether it’s buying, storing, or selling, depends on access to capital.

FAQs:

  1. Why is working capital important in agricultural trade?
    Working capital helps traders and agribusinesses manage procurement, storage, and operations without delays, ensuring smooth, timely market participation.
  2. What causes working capital gaps in agriculture?
    Timing mismatches between immediate expenses and delayed payments, along with price fluctuations, often create cash flow gaps in agri trade.
  3. How is structured trade finance different from traditional loans?
    Structured trade finance is linked to actual trade activities, such as inventory or invoices, making it more flexible and aligned with business needs.
  4. What are common financing solutions used in agri trade?
    Solutions include warehouse receipt finance, invoice discounting, supply chain financing, and working capital loans tailored to commodity cycles.
  5. How does Agriwise support working capital needs?
    Agriwise offers flexible solutions such as warehouse receipt finance, invoice discounting, and trade-linked credit to ensure timely and efficient access to capital.

Disclaimer

The content published on this blog is provided solely for informational and educational purposes and is not intended as professional or legal advice. While we strive to ensure the accuracy and reliability of the information presented, Agriwise make no representations or warranties of any kind, express or implied, about the completeness, accuracy, suitability, or availability with respect to the blog content or the information, products, services, or related graphics contained in the blog for any purpose. Any reliance you place on such information is therefore strictly at your own risk. Readers are encouraged to consult qualified agricultural experts, agronomists, or relevant professionals before making any decisions based on the information provided herein. Agriwise, its authors, contributors, and affiliates shall not be held liable for any loss or damage, including without limitation, indirect or consequential loss or damage, or any loss or damage whatsoever arising from reliance on information contained in this blog. Through this blog, you may be able to link to other websites that are not under the control of Agriwise. We have no control over the nature, content, and availability of those sites and inclusion of any links does not necessarily imply a recommendation or endorsement of the views expressed within them. We reserve the right to modify, update, or remove blog content at any time without prior notice.

warehouse receipt

Top 5 Benefits of Warehouse Receipt Financing for Farmers and Agri-Traders

January 15, 2026

Did you know that the crops sitting in a warehouse could actually earn you money before they’re even sold? That’s the power of Warehouse Receipt Financing.

Financial institutions are expected to meet the agriculture credit target of Rs 32.5 lakh crore for 2025–26.

By turning stored produce into collateral, farmers and agri-traders can access instant credit, avoid distress sales, and even sell at the most profitable time. This financial tool is helping stakeholders protect their harvest, maximise returns, and step confidently into formal markets. In India, electronic Warehouse Receipts (e-NWRs) and regulated storage systems are now unlocking significant value for agricultural stakeholders by enabling stored commodities to be used as collateral for short-term loans. But what are those benefits?

1. Improved access to working capital: One of the most immediate benefits of Warehouse Receipt Financing is the ability for farmers and traders to convert stored produce into cash without having to sell immediately. By pledging e-NWRs issued from registered warehouses/warehouse receipts by collateral managers, borrowers can access loans typically amounting to 70–75% of the commodity’s market value, helping manage input costs such as seeds, fertilisers, labour, and transport. This access to formal finance is significant in a sector where formal institutions historically offer less than 3% of agricultural credit in emerging markets.

2. Avoidance of distress sales & price timing advantage: Post-harvest periods often lead to oversupply, suppressing prices when farmers need cash the most. Warehouse Receipt Financing allows produce to be stored under certified conditions and sold later, capturing higher seasonal prices instead of resorting to low-price distress sales immediately after harvest.
For example, India’s food grain production in 2023-24 was approximately 330 million tonnes, but only about 1.24 million tonnes were financed via warehousing/e-NWR instruments, indicating huge untapped potential for price optimisation through timely selling.

warehouse receipt

3. Reduced post-harvest losses and quality preservation: Certified warehouses, governed by the Warehousing Development and Regulatory Authority (WDRA), ensure that stored commodities are graded, inspected, and preserved under optimal conditions. Proper storage reduces waste, maintains quality, and allows farmers to fetch better prices later in the season. Without access to formal warehousing and finance, farmers face significantly higher spoilage rates, up to 30–40% in unregulated storage systems worldwide.

4. Strengthened bargaining power & market participation: By delaying sales and leveraging formal receipts, farmers and agri-traders gain stronger bargaining power in the market. Instead of selling to local brokers at low prices, they can reach broader markets, including institutional and export channels, often resulting in better price realisation and income stability. Warehouse Receipt Financing also encourages farmers to become “price setters” rather than “price takers”, as they have the flexibility to choose when and where to sell.

5. Formal credit history and lower reliance on informal lending: By engaging with formal WRF mechanisms, farmers and traders build a credit history that can open the door to future loans on favourable terms. e-NWR-based financing also helps reduce reliance on informal moneylenders, who typically charge exorbitant interest rates, thereby improving the overall financial health of agrarian communities.
Moreover, WRF helps lenders better assess risk through verified commodity collateral, often resulting in competitive interest rates and structured repayment terms.

negotiable warehouse receipt

Warehouse receipt industry figures that matter

  • India’s regulated warehouse capacity reached approximately 44.8 million tonnes by March 2025, signalling expanding storage infrastructure.
  • Electronic Warehouse Receipts (e-NWRs) were issued for roughly 54 million metric tonnes of agricultural commodities, indicating growing adoption of digital instruments.
  • The warehouse receipt financing ecosystem, including negotiable receipts, was valued at around ₹35,000 crore in recent years, demonstrating substantial credit flows into agriculture.
  • Commodity valuations backed by storage receipts surged from ₹12,362 crore in FY23 to nearly ₹19,930 crore in FY25, reflecting institutional confidence and market growth. Based on current growth momentum, commodity valuations are expected to cross 24,000–26,000 crore in FY26.

How Agriwise helps farmers & agri-traders

At Agriwise, we empower farmers, traders, and agri-businesses to unlock the full potential of Warehouse Receipt Financing through a comprehensive suite of services:

  • Access to WHR (Warehouse Receipt) finance: Agriwise Finserv provides tailored financing solutions against warehouse receipts issued by the collateral manager (CM), ensuring borrowers get the cash they need without distress selling.
  • Wide network of accredited warehouses: We partner with Asia’s leading warehousing & collateral management company (Staragri). 
  • Market insights & advisory: Our platform gives real-time price trends, market data, and sell timing guidance, helping clients maximise returns on stored commodities.
  • Technology-driven transparency: Digital documentation and tracking through secure systems enhance lender confidence and streamline loan approvals.
  • Farmer education & support: From documentation help to training on using receipts and understanding loan terms, Agriwise bridges the gap between farmers and formal credit.

Conclusion

Warehouse Receipt Financing stands out as a powerful tool in modern agricultural finance, enabling farmers and agri-traders to stabilise incomes, avoid premature selling, and access formal credit with fewer hurdles. As India’s regulated warehousing ecosystem expands and digital receipts gain traction, WRF will play an increasingly pivotal role in strengthening rural economies and enhancing farm profitability. With partners like Agriwise, stakeholders can confidently leverage these financial instruments to grow sustainably and prosper in a competitive market.

FAQs

  1. What is Warehouse Receipt Financing (WRF)?
    WRF is a credit facility that allows farmers or agri-traders to pledge stored commodities in certified warehouses/professional warehouses as collateral to access short-term loans.
  2. Who can benefit from WRF?
    Farmers, agri-traders, manufacturers, exporters, importers and agribusinesses who want timely working capital, better price realisation, and reduced post-harvest losses can benefit from WRF.
  3. How does WRF help avoid distress sales?
    By storing commodities in certified warehouses and using receipts as collateral for loans, farmers can wait for better market prices before selling immediately after harvest.
  4. What types of commodities are eligible for WRF?
    Grains, pulses, oilseeds, spices, and other non-perishable agricultural products stored in WDRA-approved or accredited warehouses can be financed under WRF.
  5. How does WRF improve financial inclusion?
    WRF builds formal credit history for farmers and traders, reducing reliance on informal lenders and enabling easier access to future loans at competitive interest rates.

Disclaimer

The content published on this blog is provided solely for informational and educational purposes and is not intended as professional or legal advice. While we strive to ensure the accuracy and reliability of the information presented, Agriwise make no representations or warranties of any kind, express or implied, about the completeness, accuracy, suitability, or availability with respect to the blog content or the information, products, services, or related graphics contained in the blog for any purpose. Any reliance you place on such information is therefore strictly at your own risk. Readers are encouraged to consult qualified agricultural experts, agronomists, or relevant professionals before making any decisions based on the information provided herein. Agriwise, its authors, contributors, and affiliates shall not be held liable for any loss or damage, including without limitation, indirect or consequential loss or damage, or any loss or damage whatsoever arising from reliance on information contained in this blog. Through this blog, you may be able to link to other websites that are not under the control of Agriwise. We have no control over the nature, content, and availability of those sites and inclusion of any links does not necessarily imply a recommendation or endorsement of the views expressed within them. We reserve the right to modify, update, or remove blog content at any time without prior notice.