Tag Archives: business loan

Why is Your Credit Score Important When Applying for a Loan?

October 29, 2026

Applying for a loan is about more than filling out a form and sharing financial documents. Before a lender decides whether to approve your application, it needs to understand how you have handled credit in the past and whether you are likely to repay the amount borrowed. And this is where your credit score becomes important.

Whether you are planning to expand a business, purchase equipment, invest in agricultural operations or manage a temporary cash-flow gap, your credit history can influence how a lender evaluates your application. Understanding what your score means, what affects it, and how to maintain it can help you approach borrowing with greater confidence.

What is a credit score?

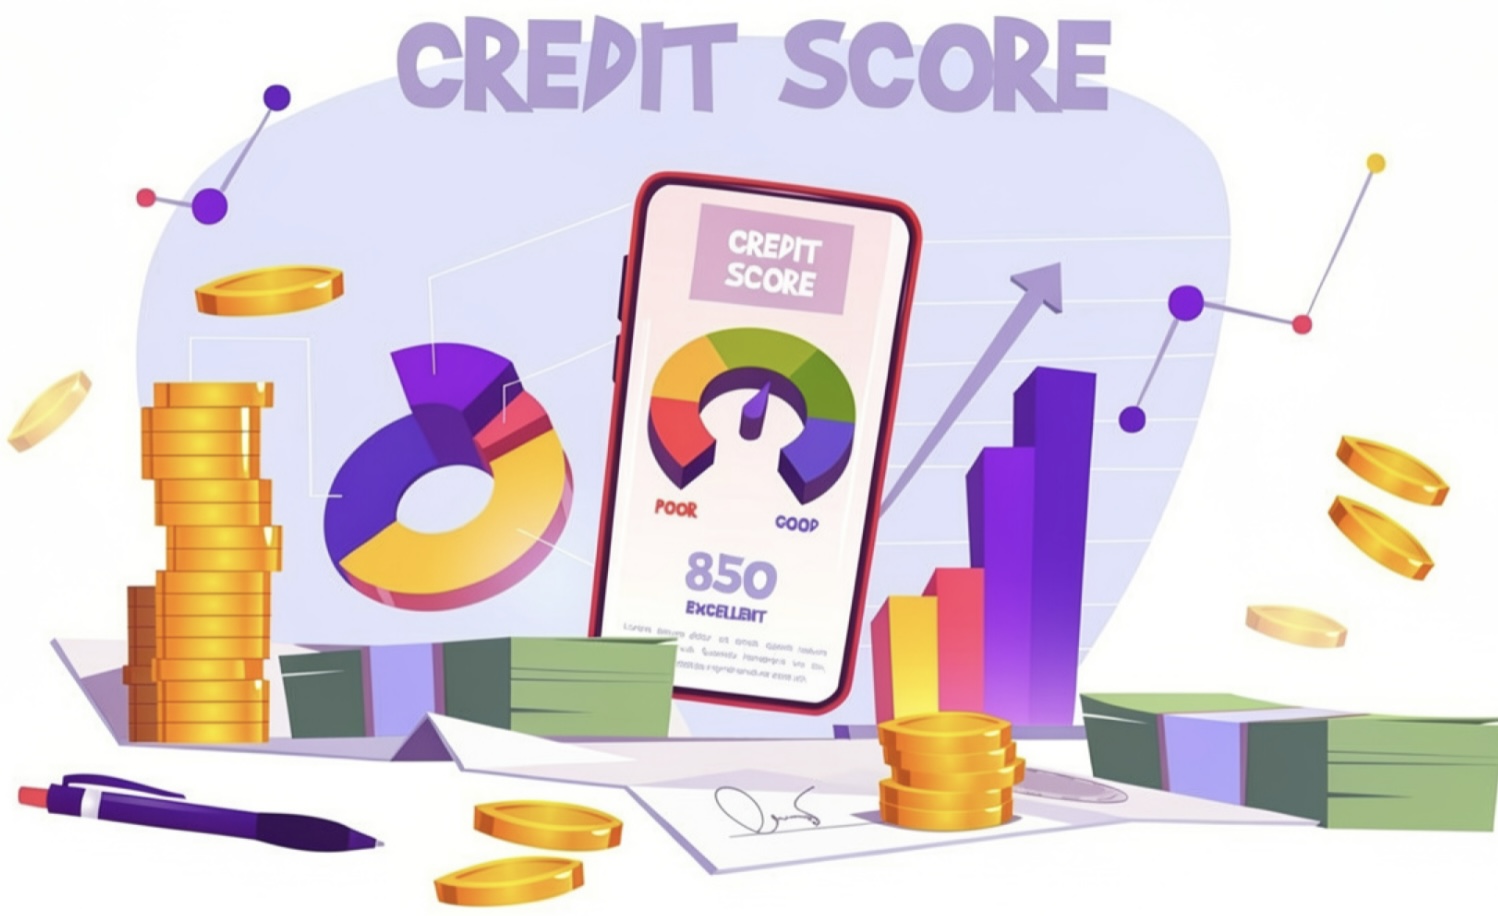
A credit score is a numerical representation of your credit history. It helps lenders assess your past borrowing and repayment behaviour. In India, the CIBIL Score is one of the credit scores used by lenders. It ranges from 300 to 900, with higher scores generally indicating a stronger credit profile. The score is calculated using information in your credit report, including loan accounts, credit card activity, repayment records and credit enquiries. Lenders use this information alongside other details to assess an applicant’s creditworthiness.

According to TransUnion CIBIL’s March 2026 report, 183 million Indians were monitoring their CIBIL Scores as of December 2025. The number of consumers checking their score for the first time had increased by 27% year-on-year, while the average score among monitoring consumers stood at 728. Nearly 45% of these consumers improved their score within six months of monitoring it.
Why is your credit score important when applying for a loan?

  1. It helps lenders assess your repayment behaviour

Your credit score gives lenders an initial indication of how you have managed previous credit commitments. A history of paying loan instalments and credit card dues on time generally supports a stronger credit profile. Repeated missed payments, defaults or high outstanding balances may raise concerns. A good score does not automatically guarantee loan approval, but it can help establish confidence in your repayment track record.

  1. It can influence your loan eligibility

Lenders have their own credit policies and eligibility criteria. Some may require a minimum score for particular loan products, while others may consider applicants with different credit profiles based on additional factors.

For example, a business owner seeking funds for expansion may have a good credit score but insufficient cash flow to support the proposed repayment schedule. The lender will need to assess both aspects. Your credit score is therefore an important part of the application, not the only deciding factor.

  1. It may affect the terms offered

A stronger credit profile can improve your position when a lender evaluates your application. Depending on the lender’s policies and the type of loan, creditworthiness may influence the terms offered.

However, there is no universal credit-score threshold that guarantees a particular interest rate, loan amount or repayment period. Income, business performance, collateral, existing obligations and lender-specific policies also matter.

  1. It can help you identify financial issues early

Checking your credit report regularly can reveal missed-payment entries, unfamiliar accounts, incorrect outstanding balances or other reporting errors.

Finding these issues early gives you an opportunity to investigate and raise a dispute where necessary, rather than discovering them when you urgently need funds.

  1. It matters for business owners too

Credit assessment is not limited to salaried individuals. Entrepreneurs, MSMEs and agricultural businesses may also be evaluated on their borrowing history, existing liabilities and financial performance.

For business-related borrowing, lenders may consider the credit profiles of relevant individuals, the business’s financial statements, cash flow, banking records and other applicable information. A healthy credit history can support the application process, while organised financial records help demonstrate the business’s ability to manage repayments.
What factors affect your credit score?

Several factors can influence your score, although their relative importance varies by credit-scoring model.

  • Payment history: Paying EMIs and credit card dues on time helps maintain a positive record.
  • Credit utilisation: Using a large proportion of your available credit limit may indicate financial pressure.
  • Length of credit history: A longer, well-managed credit history can provide more information about repayment behaviour.
  • Credit enquiries: Multiple applications for credit within a short period may warrant closer assessment.
  • Credit mix: Your combination of secured and unsecured borrowing may form part of the assessment.

It is worth remembering that income and savings are not themselves the same as a credit score. A person can earn well and still have a weak credit history, while someone with a modest income may maintain a strong repayment record.

How can you improve your credit score?

Start by checking your credit report for accuracy. Pay EMIs and card dues on time, keep outstanding balances manageable and avoid applying for several credit products without a clear need. If you have overdue accounts, work towards resolving them and maintaining consistent repayments. If an entry appears incorrect, raise a dispute with the relevant credit bureau and lender.

Most importantly, allow time for positive repayment behaviour to reflect in your credit profile. There is no reliable shortcut that guarantees an immediate improvement.
How Agriwise supports your borrowing needs

Agriwise Finserv is an RBI-registered systemically important non-banking financial company that provides financing solutions for businesses, agricultural enterprises, MSMEs and other eligible borrowers.

Its offerings include Agri Term Loans, Secured Business Loans, Warehouse Receipt Finance, Supply Chain Finance, Farmer Finance and Customised Working Capital Loans. These products address different funding requirements, from business expansion and working capital to financing against eligible agricultural commodities stored in warehouses.

When assessing an application, borrowers should understand that approval depends on the applicable eligibility criteria, credit assessment, financial position, documentation and product-specific requirements. A strong credit score can support the process, but it does not replace these checks. By understanding your credit profile before applying, you can prepare your documents, evaluate your funding needs and approach the right financing option with greater clarity.

Conclusion

Your credit score is more than a number. It is one part of the financial picture lenders use to understand your repayment behaviour and assess lending risk.

Monitoring it regularly, correcting errors and maintaining disciplined repayment habits can help you prepare for future borrowing. Whether you are funding a business opportunity or managing working capital, informed credit decisions begin well before the loan application is submitted.

FAQs

  1. What is a good credit score for a loan in India?
    A score of 750 or above is commonly considered favourable by many lenders, but requirements vary by lender and loan product. A high score does not guarantee approval.
  1. Does checking my own CIBIL Score reduce it?
    Checking your own score is generally treated as a soft enquiry and does not lower it. Credit applications made to lenders may result in hard enquiries.
  1. Can I get a loan with a low credit score?
    Possibly. Some lenders may consider applications with lower scores depending on income, repayment capacity, collateral and other factors. Approval is not guaranteed.
  1. How long does it take to improve a credit score?
    There is no fixed timeline. Improvements depend on the reasons for a low score, repayment behaviour, credit utilisation and how quickly updated information appears in the credit report.
  1. Does Agriwise offer loans based only on a credit score?
    No single score determines every application. Agriwise evaluates applications according to the relevant product’s eligibility requirements, financial assessment and other applicable lending criteria.
business loan

Loan Against Property vs Business Loan: Which is Better for MSMEs in 2026?

June 11, 2026

If you run a small or mid-sized business in India, chances are you’ve faced this question at some point: do I mortgage my property to raise capital, or do I go for a straightforward business loan? It sounds simple, but the answer can have a significant impact on your cash flow, your balance sheet, and your business trajectory for years.

Let’s cut through the noise and break it down clearly, especially in the context of where Indian MSME lending stands in 2026.

First, why does this even matter right now?

India’s MSME sector is at a critical inflexion point. According to the CRIF-SIDBI Small Businesses Report 2025, MSME credit exposure in India grew 19.3% year-on-year to ₹45.3 trillion as of June 2025, with active loan accounts rising to 6.9 crore. That’s strong headline growth, but here’s the catch.

Despite that momentum, SIDBI estimates that the sector still faces an addressable credit gap of ₹30 lakh crore, nearly 24% of total demand that formal institutions haven’t been able to meet.

That gap means millions of MSMEs are either paying too much for credit, picking the wrong product for their needs, or simply going without. Understanding the difference between a Loan Against Property (LAP) and an unsecured business loan isn’t just a financial decision but a strategic one.

loan against property for MSME

What is a Loan Against Property?

A Loan Against Property (LAP) is a secured loan where you pledge residential or commercial property as collateral. In return, you get access to higher loan amounts, longer repayment tenures, and significantly lower interest rates compared to unsecured credit.

As of 2026, LAP interest rates in India range from 8.45% to 15% per annum, depending on the lender, borrower profile, and property type. Major banks are offering rates from 9% to 13% for prime borrowers following the RBI’s accommodative rate stance. The repo rate now stands at 5.5% after successive cuts in 2025.

The Indian LAP market itself was valued at USD 758 billion in 2024 and is forecast to reach USD 2,369 billion by 2033, growing at a CAGR of 13.5%. Rising MSME credit demand in Tier 2-4 cities is one of the key growth drivers, as businesses in smaller markets increasingly leverage their property assets to fund expansion.

LAP is best suited for: capital-heavy needs like buying new facilities, purchasing equipment, long-term infrastructure investment, or scaling operations where you need a large ticket size and can afford longer processing timelines.

What is an unsecured business loan?

An unsecured business loan (often called an MSME loan) doesn’t require collateral. It’s faster to process, easier to access, and designed for immediate liquidity needs, but it comes at a cost. Interest rates on unsecured business loans typically start from 16% per annum and can go considerably higher depending on your risk profile. That’s a meaningful premium over LAP, sometimes 5 to 7 percentage points, which adds up significantly over a multi-year loan.

The trade-off is speed and simplicity. Business loans can be disbursed quickly, often without property documentation, and are widely available through banks, NBFCs, and government schemes like MUDRA and CGTMSE. For working capital shortfalls, emergency procurement, or short-cycle needs, they work well.

Business loans are best suited for: short-term working capital, bridging gaps between receivables and payables, or situations where you don’t want to (or can’t) pledge a property.

LAP vs Business Loan: The key differences at a glance

Factor

Loan Against Property Unsecured Business Loan

Interest Rate

8.45% – 15% p.a.

16%+ p.a.

Loan Amount

Higher (up to 60-70% of property value)

Lower ticket sizes

Tenure

Up to 15 years

Typically 1-5 years

Processing Time

Longer (property valuation required)

Faster

Collateral

Property required

Not required

Best For Long-term capital, expansion

Short-term working capital


So, which should an MSME choose in 2026?

The honest answer: it depends on what you need the money for and how urgently you need it.

If you’re investing in something that will generate returns over the medium to long term, new machinery, a bigger processing facility, or agricultural infrastructure, LAP’s lower interest rate will save you substantially more over the tenure of the loan. The upfront effort of property documentation pays for itself.

If you need cash fast to meet a vendor payment, bridge a seasonal working capital gap, or respond to a market opportunity with a short cycle, a business loan’s speed often outweighs its higher cost.

Many smart MSMEs use both: LAP for long-term structural investments, and a working capital line for day-to-day operational flexibility. The goal is to match the type of credit to the purpose. Using expensive short-term money for long-term assets is one of the most common (and costly) mistakes small businesses make.

What’s Agriwise’s role in all this

For agri-linked MSMEs, the decision is often more nuanced because the credit need is tied to seasonal cycles, commodity prices, storage infrastructure, and supply chain dynamics that a standard bank product isn’t designed to handle.

This is exactly the space Agriwise, the NBFC arm of StarAgri, is built for. Agriwise brings a deep understanding of the agri value chain to credit underwriting, offering:

  • LAP: structured, property-backed financing for agri expansion, procurement scale-up, or infrastructure development, with rates designed to be competitive for agri-linked businesses
  • Warehouse Receipt Finance: working capital against commodities stored in StarAgri’s 2,200+ warehouses, providing liquidity without forced selling at low post-harvest prices
  • Supply Chain Finance: unlocking cash tied up in receivables for agri MSMEs, traders, and processors
  • Solar Finance: financing for renewable energy adoption among farmers and agri businesses

Agriwise has disbursed over ₹2,500 crore across 5,500+ customers and works with various banking partners, building a credit infrastructure that understands what an agricultural season actually looks like.

The difference between a good financing decision and a poor one is often just context. A lender that understands your industry, your cash flow patterns, and your assets can structure credit that works, not just credit that’s available.

business loan for MSME

Conclusion 

In 2026, both LAP and business loans will have a clear place in the MSME financing toolkit. LAP wins on cost for long-term, higher-value needs. Business loans win on speed for short-term, operational requirements. The mistake isn’t choosing one over the other. It is choosing the wrong one for the wrong purpose.

With India’s MSME credit gap still at ₹30 lakh crore, getting this decision right matters, not just for your business, but for the broader formalisation of Indian enterprise finance.

If you’re an agri-linked MSME trying to figure out which product fits your situation, Agriwise can help you navigate that decision, with the sector knowledge to back it up.

FAQs

  • What is the main difference between a Loan Against Property and an unsecured business loan?
    A LAP requires property as collateral but offers lower interest rates (8.45–15% p.a.) and higher loan amounts. An unsecured business loan needs no collateral but typically starts from 16% p.a. and suits shorter-term, faster-turnaround needs.
  • Which loan option is better for an agri-linked MSME?
    For long-term investments like infrastructure or equipment, LAP’s lower rate saves significantly over the tenure. For seasonal working capital or short-cycle needs, Agriwise’s warehouse receipt finance is often a smarter, faster alternative to either.
  • What is warehouse receipt finance, and how is it different from a traditional loan?
    It’s credit extended against commodities stored in a recognised warehouse, rather than against property or credit history. Farmers and agri-MSMEs can borrow against stored produce through Agriwise instead of being forced to sell at low post-harvest prices.
  • How does Agriwise assess creditworthiness for agri-MSMEs?
    Agriwise uses proprietary credit models built on 16+ years of agri-sector repayment data, accounting for seasonal cash flows and commodity price cycles, resulting in NPAs consistently below 1%, well below industry norms.
  • Can an MSME use both a Loan Against Property and a business loan at the same time?
    Yes, and many do. LAP works well for long-term structural investments, while a working capital line handles day-to-day operations. The key is matching the type of credit to the purpose. Mixing the two up is one of the most common and costly financing mistakes MSMEs make.

Disclaimer

The content published on this blog is provided solely for informational and educational purposes and is not intended as professional or legal advice. While we strive to ensure the accuracy and reliability of the information presented, Agriwise make no representations or warranties of any kind, express or implied, about the completeness, accuracy, suitability, or availability with respect to the blog content or the information, products, services, or related graphics contained in the blog for any purpose. Any reliance you place on such information is therefore strictly at your own risk. Readers are encouraged to consult qualified agricultural experts, agronomists, or relevant professionals before making any decisions based on the information provided herein. Agriwise, its authors, contributors, and affiliates shall not be held liable for any loss or damage, including without limitation, indirect or consequential loss or damage, or any loss or damage whatsoever arising from reliance on information contained in this blog. Through this blog, you may be able to link to other websites that are not under the control of Agriwise. We have no control over the nature, content, and availability of those sites and inclusion of any links does not necessarily imply a recommendation or endorsement of the views expressed within them. We reserve the right to modify, update, or remove blog content at any time without prior notice.