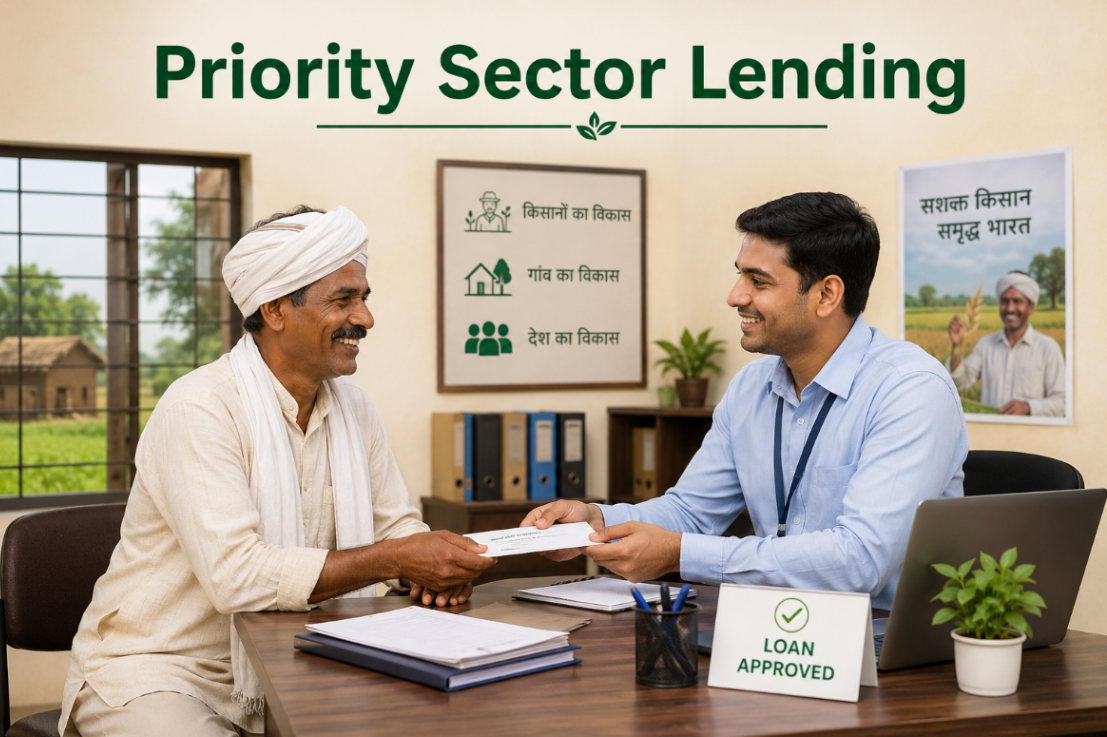
Agriculture needs capital long before it generates revenue.
A farmer may need money for inputs. A trader may need working capital to procure produce. A warehouse operator may need funds for infrastructure, while an agricultural business may need liquidity while waiting for invoices to be paid.
This is why agricultural credit is much broader than the traditional idea of a “farm loan”.
Agriculture Business Loans can support businesses operating throughout the agricultural value chain. And in India, Priority Sector Lending (PSL) plays an important role in directing institutional credit towards agriculture and other strategically important sectors.
Here is what agricultural businesses should understand.
What is Priority Sector Lending?
Priority Sector Lending is a framework established by the Reserve Bank of India (RBI) under which banks are required to direct a prescribed portion of their lending towards identified priority sectors.
These include agriculture, MSMEs, education, housing, renewable energy and certain other categories.
Under current RBI requirements, applicable commercial banks are required to allocate 18% of Adjusted Net Bank Credit (ANBC) or Credit Equivalent of Off-Balance Sheet Exposures (CEOBSE), whichever is higher, towards agriculture. A 10% sub-target applies to Small and Marginal Farmers. The purpose is to ensure productive sectors such as agriculture have stronger access to formal credit.
Which agricultural activities can qualify?
Agricultural lending under PSL is not restricted to crop cultivation. Depending on the borrower, activity, lender and prevailing RBI eligibility requirements, agriculture-related lending can cover farm credit, agricultural infrastructure and ancillary activities.
This broader framework is important because modern agriculture includes an entire commercial ecosystem: farmers, FPOs, processors, traders, warehouses, input businesses and other enterprises.
Why do agriculture businesses need specialised loans?
An agricultural business rarely has the same cash-flow pattern as a conventional retail or service business. Procurement may be highly seasonal. Inventory may remain stored for months. Payments may depend on harvest cycles. Commodity prices can change between procurement and sale.
Consequently, Agriculture Business Loans should ideally reflect the actual working-capital cycle of the business rather than simply applying a generic lending structure.
Common financing requirements in agriculture
Different agricultural businesses require finance for different purposes.
- Working Capital: Businesses purchasing commodities, inputs or raw materials may require short-term liquidity to manage procurement and operating expenses.
- Warehouse Receipt Finance: Stored agricultural commodities may provide the basis for financing, allowing eligible borrowers to unlock liquidity against inventory rather than immediately selling produce.
- Invoice Financing: Businesses supplying agricultural goods to buyers may face a gap between delivery and payment. Invoice-based financing can help manage this period.
- Asset-backed Finance: Agricultural entrepreneurs may also require longer-tenure finance for business expansion, property-backed requirements or infrastructure investments.
Understanding the purpose of borrowing is therefore the first step towards selecting the right financing structure.
What do lenders evaluate?
Approval is never based only on whether a business operates in agriculture.
Lenders generally evaluate factors such as the borrower’s business profile, repayment capacity, cash flows, credit history, existing liabilities, documentation, collateral where applicable and the underlying purpose of the loan.
Agricultural lenders may additionally consider seasonality, commodity cycles, inventory quality and procurement or sales patterns. Good documentation and transparent financial records can therefore make a significant difference.
How Agriwise supports agricultural businesses
As agricultural value chains become more organised, specialised lenders are developing financing solutions around their unique requirements.
Agriwise Finserv operates within this ecosystem with products including Warehouse Receipt Finance, Invoice Bill Discounting, Farmer Financing, Loan Against Property, and customised working-capital solutions.
Agriwise has disbursed more than ₹2,500 crore across 5,000+ customers and works with leading banking partners across India. Its customised working-capital approach is particularly relevant for agricultural enterprises because funding can be structured around the business profile, funding requirement, repayment capacity and working-capital cycle.
Choosing the right agriculture business loan
Before borrowing, businesses should ask a few practical questions: What exactly will the funds be used for? How quickly will the investment generate cash? Is the requirement seasonal or long-term? And what repayment structure fits the business cycle?
The right loan should not simply provide capital. It should fit the economics of the business.
As agriculture becomes increasingly connected with processing, warehousing, logistics and technology, access to appropriate formal credit will remain essential.
Agriculture Business Loans under India’s broader priority-sector ecosystem can help bridge that gap, enabling agricultural enterprises to invest, operate and grow with greater financial flexibility.
FAQs
- What are Agriculture Business Loans?
They are financing solutions designed to meet capital requirements of eligible businesses operating within agriculture and allied value chains. - Is agriculture covered under Priority Sector Lending?
Yes. Agriculture is one of the major categories recognised under RBI’s PSL framework. - What is the PSL target for agriculture?
Applicable banks have an agriculture target of 18% of ANBC or CEOBSE, whichever is higher, subject to RBI guidelines. - Can agricultural businesses get working-capital finance?
Yes, subject to lender eligibility and assessment, working-capital facilities can support procurement, inventory and other operational requirements. - What financing solutions does Agriwise provide?
Agriwise offers solutions including Warehouse Receipt Finance, Invoice Bill Discounting, Farmer Financing, Loan Against Property, and customised working-capital financing.