Agriculture rarely runs on a convenient financial calendar. Seeds need to be purchased before sowing, fertilisers must be arranged at the right time, labour payments cannot always wait, and unexpected weather conditions can bring additional expenses.
For smallholder farmers, managing these costs can be particularly challenging. Limited savings, irregular cash flows and lengthy loan procedures can make timely access to formal credit difficult.
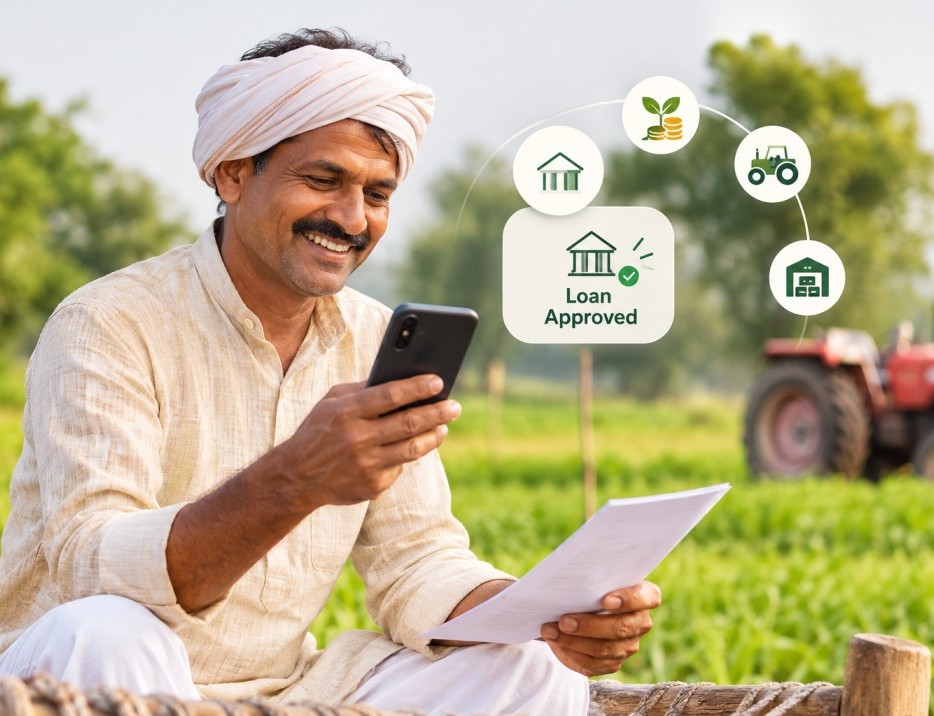
This is where digital agricultural lending is changing the picture. Online applications, simplified documentation and technology-enabled lending processes are making it easier for farmers to explore formal credit options without depending entirely on traditional application methods.
But how can smallholder farmers access instant agricultural loans online? What documents do they need? And how can they identify a loan that actually suits their requirements?
Let’s break it down.
Why is timely agricultural credit important
Agricultural expenses are closely connected to crop cycles. Farmers often need working capital weeks or months before harvesting their produce. However, their income generally arrives only after the crop is sold. This creates a financial gap.
Without timely credit, farmers may postpone essential purchases, reduce input usage or turn to informal borrowing. Such decisions can affect productivity and increase financial pressure.
The scale of institutional agricultural lending in India highlights the importance of accessible credit.
According to the Ministry of Agriculture, more than 7.72 crore Kisan Credit Cards were active across India, with outstanding loans of approximately ₹10.2 lakh crore. The government has also enhanced the crop loan limit under the Modified Interest Subvention Scheme from ₹3 lakh to ₹5 lakh for 2025–26. The collateral-free credit limit has been increased to ₹2 lakh per borrower.
How can farmers apply for instant agricultural loans online?
Digital lending has made it easier to initiate a loan application and understand available credit options. Although the exact process differs across lenders, farmers can generally follow these steps.
Step 1: Identify the purpose of borrowing
Before applying, determine why the funds are needed. Is the requirement related to seeds and fertilisers, irrigation equipment, farm development or working capital? Understanding the purpose helps identify the appropriate loan category.
Step 2: Explore regulated lending institutions
Farmers can visit the official websites of banks and regulated NBFCs to compare available agricultural loan products. Look at the eligibility conditions, loan amounts, repayment schedules, applicable interest rates and processing requirements.
Step 3: Submit an online application
Most digital application processes begin with basic information such as the applicant’s name, contact details, location, occupation and proposed loan requirement.
Step 4: Upload the required documents
Depending on the loan type, the lender may request identity proof, address proof, bank statements, land-related documents and details of agricultural activities.
Step 5: Complete verification
The lender evaluates the application, verifies the submitted information and assesses the applicant’s repayment capacity. Additional documentation may be required.
Step 6: Review the loan offer
Once approved, carefully examine the sanctioned amount, interest rate, processing fees, repayment schedule and other applicable conditions before accepting the offer.
It is important to remember that applying online does not automatically mean instant approval. Loan sanction and disbursement depend on the lender’s assessment and verification process.
What types of agricultural loans can farmers explore?
Not every farming requirement needs the same kind of financial support. Choosing the right product can help borrowers manage repayment more effectively. Here are some common options.
- Crop and input loans: These help farmers manage seasonal cultivation expenses, including seeds, fertilisers and other agricultural inputs.
- Agricultural term loans: These are designed for longer-term investments in eligible agricultural assets and infrastructure.
- Working capital loans: These help manage recurring operational expenses and short-term cash flow requirements.
- Warehouse receipt finance: Farmers and other eligible commodity owners can use stored agricultural produce as collateral to access credit without immediately selling their inventory.
- Kisan Credit Card: The KCC provides a revolving credit facility for eligible cultivation and allied agricultural requirements, with provisions for post-harvest and other specified expenses.
What should farmers check before applying online?
Convenience is important, but financial clarity matters even more. Before applying for an agricultural loan, farmers should consider the following:
- Verify the lender: Use official websites and authorised application channels. Check whether the institution is regulated appropriately.
- Understand the total cost: Review interest rates, processing fees, insurance charges and penalties.
- Check repayment conditions: Ensure repayment dates are realistic in relation to expected agricultural income.
- Understand eligibility: Landholding, income, collateral and credit history requirements can differ between products.
- Protect personal information: Never share OTPs, passwords or banking credentials with unknown callers or unofficial websites.
Farmers should also be cautious about advertisements promising guaranteed approval or immediate disbursement without verification.
How digital platforms are widening credit access
India’s formal credit ecosystem is increasingly supported by digital infrastructure.
One example is the government’s Jan Samarth portal, which provides a unified digital gateway for applications under 16 credit-linked government schemes. The portal covers several categories, including Kisan Credit Card loans, agricultural infrastructure finance and electronic warehouse receipt financing.
However, access to digital applications must go hand in hand with suitable credit products. A farmer’s financial requirements are different from those of a processor, trader or agricultural enterprise. That is why specialised agricultural lending remains important.
Agriwise Farmer Finance: Credit for Different Stages of Farming
Agricultural finance needs do not begin and end with sowing. Farmers require funds at different points in the crop cycle, and a financing solution must account for these changing requirements. Agriwise Farmer Finance is designed to support eligible farmers with financial requirements related to agricultural inputs, cultivation and post-harvest activities. Its focus is to provide timely financial support through a simple application journey and flexible repayment options, helping farmers manage expenses across different stages of their farming operations.
The key features of Farmer Finance include:
- Support for farming requirements: Financing designed around needs such as agricultural inputs, cultivation expenses and post-harvest requirements.
- Simple application process: A streamlined application journey that helps farmers initiate their financing request with greater convenience.
- Flexible repayment: Repayment options designed with farming requirements and cash flow considerations in mind, subject to the applicable loan terms.
- Assessment-led lending: Eligibility is evaluated based on the farmer’s profile, agricultural activity, repayment capacity, documentation and applicable lending criteria.
Conclusion
Timely credit can make a meaningful difference to how smallholder farmers manage their agricultural operations. Digital applications are helping reduce the initial barriers to formal finance, while specialised lending products address different cultivation, infrastructure and working capital requirements. The real advantage, however, lies in choosing credit that matches the purpose of borrowing and the ability to repay.
With the right financial support, farmers can focus less on managing immediate cash shortages and more on building productive and sustainable agricultural operations.
FAQs
- Can smallholder farmers apply for instant agricultural loans online?
Yes. Farmers can explore online applications through banks and regulated financial institutions. Approval depends on the lender’s eligibility criteria, documentation and verification process. - What documents are required for an online agricultural loan?
Common documents include identity and address proof, bank statements, land-related records and details of agricultural activities. Requirements vary depending on the lender and loan product. - Are instant agricultural loans approved immediately?
Not necessarily. Digital applications can simplify the initial process, but lenders must still verify information, assess eligibility and complete their credit evaluation before sanction and disbursement. - What is the difference between a crop loan and an agricultural term loan?
Crop loans generally cover short-term cultivation expenses, while agricultural term loans support longer-term investments in eligible farm assets and infrastructure. - How does Agriwise help farmers access instant agricultural loans?
Agriwise offers Farmer Financing for eligible agricultural input and working capital requirements, along with other products such as Warehouse Receipt Finance and Supply Chain Finance. Interested borrowers can submit enquiries through its official website.